Home » blogs » Providing Support For Retirees

Providing Support For Retirees

We want to make sure you are aware of the changes in the minimum pension rules recently introduced because of COVID19.

Container
Melanie-Basta-200x200-Square.jpg

Written by

BERIVAN DUBIER
Last Updated Apr 15, 2020
|
Fact checked
|

Invested In You

Your financial journey is an inherent part of your well-being and happiness. When you feel confident and your finances are healthy and secure, the other areas of your life are balanced and supported.

This is why our professional services go well beyond tax compliance and corporate accounting services. At Curve Accountants, our comprehensive approach is designed to present you with proactive, tailored advice that allows you to make smart financial decisions. From strategies for managing wealth and minimising tax to succession planning and business restructuring, we are committed to offering advice tailored to your unique situation.

Providing support for retirees

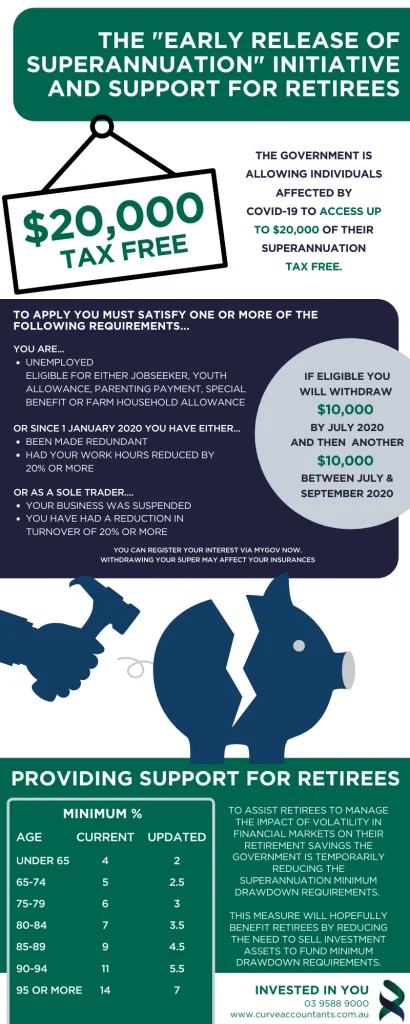
To assist retirees to manage the impact of volatility in financial markets on their retirement savings the Government is temporarily reducing the superannuation minimum drawdown requirements. The pension minimum for account-based pensions and similar products will be 50 per cent less for the 2019–20 and 2020–21 income years. This measure will hopefully benefit retirees by reducing the need to sell investment assets to fund minimum drawdown requirements.

Age Default minimum draw down rates (%) Reduced rates by 50% for 2019-20 and 2020-21
Under 65 4 2
65-74 5 2.5
75-79 6 3
89-84 7 3.5
85-89 9 4.5
90-94 11 5.5
95 or more 14 7

The "early release of superannuation" initiative and support for retirees

Should you require any assistance in determining whether you have already paid the required minimum pension for this financial year please contact our office. We are here to help.

Helpful tip:

icon

Review your retirement income, superannuation, and government entitlements regularly to ensure they continue to meet your needs. Changes in your financial circumstances may affect your eligibility for certain benefits. Seeking advice can help you make informed retirement decisions.

BERIVAN DUBIER

DIRECTOR

Reviewed by

David-Rayfield-200x200-Square.jpg

SEAN DWYER

DIRECTOR
CPA and financial adviser for over 25 years. Loves to help businesses grow. Dad, jogger, cyclist, windsurfer and bad skier.

Edited by

David-Rayfield-200x200-Square.jpg (1)

Alix Dower

PRACTICE MANAGER

I’m like a ninja with spreadsheets and a detective with data, passionate about problem solving and providing solutions. Experienced Practice Manager with a demonstrated history of working in the financial services industry.
Are you a business or medical professional who’s ready to secure your financial future? Book a free consultation with the team at Curve Accountants today!

Free eBook Download

David-Rayfield-200x200-Square.jpg (2)

Starting A Medical Practice

David has extensive experience in writing, editing and marketing before joining iSelect in 2023 as Digital Editor. When not making our content better, you can find them browsing log cabins for sale in the forest.
REQUEST DOWNLOAD

David-Rayfield-200x200-Square.jpg (3)

Buying An Established Medical Practice

A mark of a good practice is a demonstrable ability to produce an above-average return for its owners. This ebook outlines the importance of this and strategies for prospective buyers..
REQUEST DOWNLOAD

FAQ

Does the 50% reduction in minimum pension drawdowns still apply?
No. The temporary reduction described in this April 2020 article applied for the 2019–20 through 2022–23 financial years. Standard minimum payment rates resumed from 2023–24. Retirees and SMSF trustees should calculate the minimum for the income year they are dealing with rather than continue using the reduced figures.
What are the current minimum rates for an account-based pension?
The standard annual rates are 4% if you are under 65, 5% at ages 65–74, 6% at 75–79, 7% at 80–84, 9% at 85–89, 11% at 90–94 and 14% at 95 or over. These are minimum percentages, not the amount of tax you pay. Different pension products can have different rules, so check the type of income stream.
How is my minimum pension payment calculated?
For an existing account-based pension, the fund generally applies the percentage for your age on 1 July to the pension account balance on that date, then rounds the annual amount under the pension rules. For example, a 67-year-old with a $480,000 balance on 1 July has a 5% minimum, or $24,000 for the year. Confirm the balance, age and payment amount for each pension account.
What if my pension started partway through the financial year?
The first year’s minimum is generally calculated using the pension balance when it starts and the applicable age rate, then prorated for the days remaining in the financial year. Special rules can apply for a pension starting very late in June. Ask the fund or your adviser for the amount rather than using a full-year estimate.
Can I take less than the minimum if investment markets fall?
Market volatility does not itself reduce the current statutory minimum. You may choose when and how to arrange the required payments within the year, subject to the pension terms and cash availability, but the minimum must be paid by 30 June. Review liquidity early if the fund holds assets that may be difficult to sell.
What if I have more than one SMSF pension?
The minimum must be met for each pension separately. Taking more than the minimum from one pension does not automatically make up a shortfall in another. Trustees should keep separate member and pension records, review payments against each account and check the status of any commutation before treating a withdrawal as a pension payment.
Do lump sum withdrawals or pension commutations count towards the minimum?
A partial commutation of an account-based pension does not count towards its annual minimum payment. Before fully commuting a pension, trustees generally need to ensure the required minimum pension payment has been made, subject to limited exceptions. Record the member’s instructions and the character of each payment before it is made.
What happens if the minimum is not paid by 30 June?
The pension may be treated as having stopped at the start of that income year for tax purposes. An SMSF could lose its exempt current pension income treatment for the assets supporting that pension, and transfer balance reporting may be affected. The ATO has a limited exception for certain small, honest mistakes and circumstances outside a trustee’s control; seek advice promptly rather than assuming a later payment fixes the shortfall.

Related Blogs

Find Out How Curve Accountants Can Help

Owning your own business or practice is a defining characteristic of who you are. By partnering with Curve Accountants to support you in your business finances, together we can have open and honest conversations about money, and bring fresh thinking and creative ideas to amplify the exact financial goals you want to work towards. Just as your own customers, clients, or patients trust you implicitly to provide them with the best advice and outcome, we believe the same should be achieved for your financial health. Get in touch with us today to book a free consultation with an industry-accredited tax and business accountant Melbourne-wide, from either our head office in Sandringham, or our office.
Curve Accountants office reception