
Aligning your practice insurance coverage to your business structure
Curve helps many practice owners to design and set up an optimal business structure considering tax implications, asset protection, legal liabilities and many other factors. Contemporary operating models make use of multiple legal entities to meet the needs of owners. These can include a collection of
entities such as :

Written by

Invested In You
This is why our professional services go well beyond tax compliance and corporate accounting services. At Curve Accountants, our comprehensive approach is designed to present you with proactive, tailored advice that allows you to make smart financial decisions. From strategies for managing wealth and minimising tax to succession planning and business restructuring, we are committed to offering advice tailored to your unique situation.
- A Self Managed Super Fund
- Discretionary Trusts
- Unit Trusts
- Proprietary Limited Companies
These entities may interact with revenue generating clinical practitioners who operate as contractors to one or more entities or as employees as one or more entities.
Practice owners use an experienced team at Curve help to establish and manage the intricate details of the legal entities and how they work collectively to achieve the best financial outcomes. Most practice owners would not be able to do this complex work unassisted. However, when it comes to arranging insurance for the business, many owners try arrange this themselves or via a broker that is not experienced with the unique operating models of this sector.
The Legal Structures used – and the Ownership of each legal entity – are critical considerations when arranging business insurance. If the insurance arrangement is not aligned with the operating model then coverage could be void when it comes time to make a claim.
This is why we value our clients working with a specialist insurance broker in this sector as they understand the work we do and can connect our clients with the right insurers and arrange the cover in the right way. This avoids surprises when it comes to a claim (which they help with also).
Experien General Insurance Services (Experien) is this broker who manages business insurance for over 1,000 medical and dental practices across Australia. In this article they discuss mistakes that they commonly see when first engaging new clients who have existing policies.
Experien know that many Practice Owners commonly have a business model that involves Multiple Legal Structures such as :
- A SMSF that may own the business property with a unique Trust name and Trustee
- The business property may be one lot (of many) in a larger building, or it could be a free standing property and could also be of other formats
- A Trading Entity that commonly will lease from the SMSF as the property owner
- The trading entity may be an administration entity with an owner that could be a Family Trust (with its own unique Trustee) or one of several other options
- The trading entity will commonly have a Trading Name that differs from the Legal Name of the owner of the trading entity
- The trading entity may contract with one or more other practitioners – who are not employees of the trading entity
- The ultimate controller (owner) of the trading entity –may also contract individually as a practitioner in his or her own right.
Experien use diagrams like the first one shown below to “draw” this out and help clients to understand the insurance considerations arising. The business insurance (property and liability) implications of structures are then explained to clients.

Mistakes can commonly be seen with :
– Public Liability Insurance,
– Business Interruption Insurance and
– Property Insurance.
Experien note that the frequency of a mistake being made in arranging insurance is HIGH and the consequence of a mistake is MATERIAL in that a claim may not be paid. It is dangerous for Practitioners to try arrange insurance themselves with such structures.
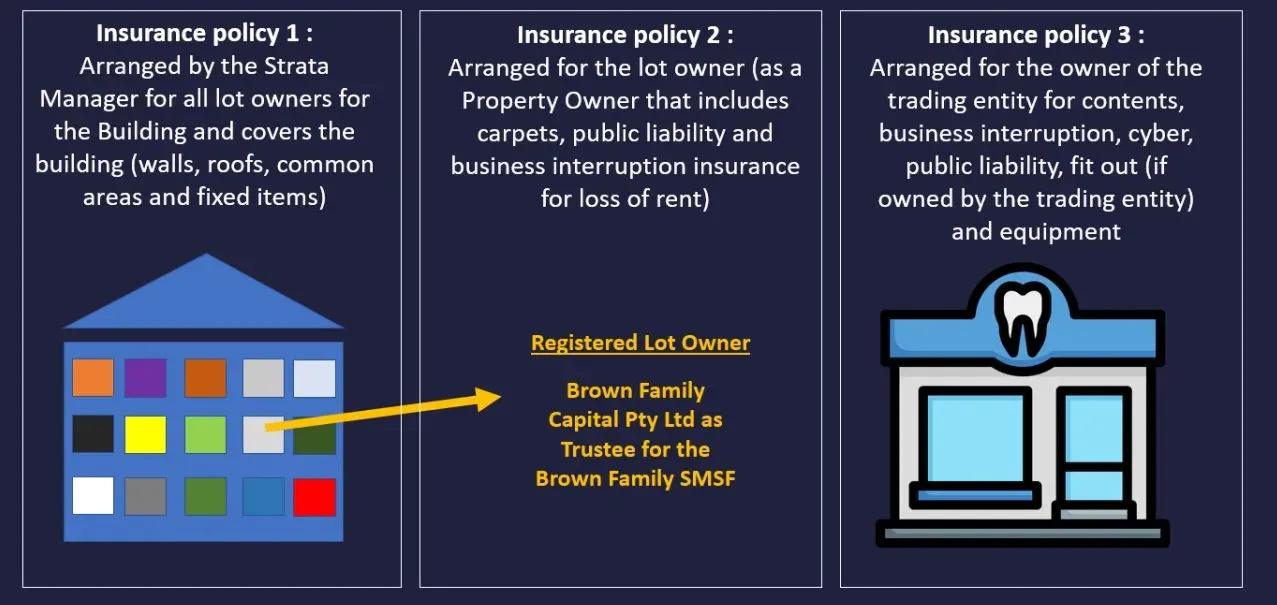
One key theme is that multiple policies may be needed – and all covers may not be able to be squeezed into one policy (without affecting coverage)
Case Study
Consider a practitioner who established his dental business – in a larger medical centre – where there are many other practices in the same building. The building was divided into individual LOTS under a STRATA scheme with each LOT owner owning their suite. Suppose this Practitioner, Dr Brown, bought one of the lots using finance from a bank.

The client used his SMSF to borrow the money and the SMSF became the property owner of the LOT. Note that the name of the owner needs to be carefully noted in full as per the above diagram. People can make a mistake of just thinking the owner is the “Brown Family SMSF” and this is mistake and incomplete. The owner must be the Brown Family Capital Pty Ltd as Trustee for the Brown Family SMSF.
The client then established his Dental practice business (the TRADING ENTITY) as its own legal entity. He named this entity with a specific LEGAL name of Brown Smiles Pty Ltd and that LEGAL name has a catchy “badge” for marketing purposes which is known as a TRADING NAME – Your Dental Care.
The TRADING NAME is NOT the LEGAL name. The LEGAL name is more important with regards to the insurance arrangement. The Trading Entity will LEASE the premises from the LOT owner. Despite it being associated with one common person – DR Brown – the nuances of the separate legal entities are of great importance with the insurance set up.
In the example below, the trading entity is owned by a family trust (Dr B Capital as Trustee For the Brown Clan Family Trust.
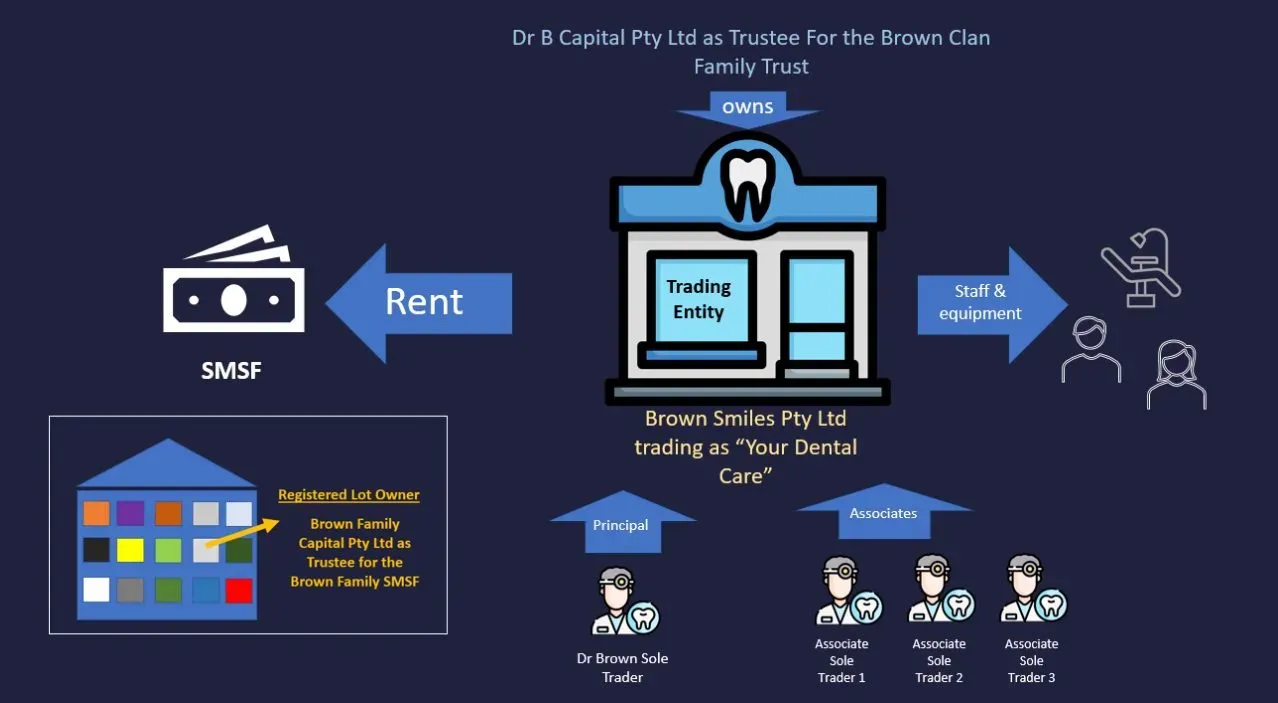
In this example, at LEAST 3 separate insurance policies will need to be set up to arrange commonly selected coverages.
We have recently seen many examples of what can go wrong when this structure is not used. Some examples include :
1. Policy #2 was not arranged. Only policy 1 and policy 3 was arranged. There was a water damage incident and the CARPETS of the practice were ruined. The client expected policy 3 to respond to the CARPET damage but the CARPETS are legally owned the LOT owner and the LOT owner should have a policy for that – but did not.
2. Trying to squeeze the LOT owner and the Trading Entity owner and their respective items to be insured under 1 policy with 2 insured names. This is not allowed by the insurers and could avoid a claim. It is only (potentially) allowed if the two separate entities have common directors or common beneficial owners.
3. The client thinking they had cover for LOSS OF RENT should the lot be damaged. They did not have the cover because they did not arrange the lot owner under its own policy – trading as a property owner.
We also see examples of Principal Clinicians contracting to the trading entity but fail to arrange public liability for their own patients.
If you want to engage Experien for a complimentary review of your existing insurance then you can reach out to Lloyd Levin via email or on 425 791 656
Please note
This is general information and you should not act on it, or rely on it, without obtaining personal advice. Always read the product disclosure statement (PDS) issued by an insurer before considering to take out insurance. General insurance services are provided by Experien General Insurance Services Pty Ltd ABN 77 151 269 279 AFS Licence No. 430190 (EGIS) trading as Experien Insurance Services. Experien and Curve are not related business entities.
Helpful tip:

Review your insurance arrangements whenever your business structure changes or your practice expands. Make sure your policies provide appropriate cover for your legal and financial risks. Regular reviews can help identify gaps in coverage before they become costly issues.
BERIVAN DUBIER
DIRECTOR
Reviewed by

SEAN DWYER
Edited by

Alix Dower
PRACTICE MANAGER
Free eBook Download

Starting A Medical Practice
David has extensive experience in writing, editing and marketing before joining iSelect in 2023 as Digital Editor. When not making our content better, you can find them browsing log cabins for sale in the forest.
REQUEST DOWNLOAD

Buying An Established Medical Practice
REQUEST DOWNLOAD
FAQ
Why does my practice’s business structure matter for insurance?
Should the policy use my trading name or legal entity name?
Give your broker or insurer the full legal names of the relevant companies, trustees and individuals, as well as any trading names. A trading name identifies the practice to the public but is not necessarily the entity that owns the property or runs the business. Ask the broker to confirm how each insured party is shown on the policy schedule.
What if my SMSF or a trust owns the practice premises?
Will one policy cover the property owner and the practice operator?
Who should insure fit-outs, carpets and equipment?
What is the difference between business interruption and loss of rent?
Are contractors and principal clinicians covered by the practice policy?
When should I review my practice insurance arrangements?
Related Blogs

How Tax Deductions and Offsets Work in Australia
Understanding the difference between tax deductions and tax offsets can help you make better financial decisions and avoid paying more tax than necessary. While both can reduce...

2026-27 Federal Budget – What the Federal Budget means for you, your family, and your business
BERIVAN DUBIER Last Updated May 13, 2026 | Fact checked | Your financial journey is an inherent part of your well-being and happiness. When you feel confident and your finances...

Payday Super FAQs for Small Business Clients
From 1 July 2026, the way employers pay super is changing. These FAQs explain what Payday Super means for your business, what’s different, and what you need to do to get...
Find Out How Curve Accountants Can Help
